-
Shop
- Advanced Technologies
- AI Skills for Creators & Freelancers
- AI Client Management
- AI Ethics
- AI Mindset
- AI Tools & Prompts
- AI Writing & Content Creation
- Audio, Voice & Music
- Design & Visual Creation
- Email, Messaging & Communication
- Freelancing & Business
- Marketing, Ads & Conversion
- Productivity, Workflow & Automation
- SEO & Search Optimization
- Social Media Content & Growth
- Strategy, Planning & Analytics
- Video Creation & Editing
- AI Skills Mastery 2026 Collection
- Bathroom
- Best-Sellers
- Car Accessories
- Confidence
- Dating & Social Skills
- Digital Resources
- Easter Products
- Education & Learning
- Family & Parenting
- Fashion
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Electronics
- Home Supplies
- Jewelry
- Kids & Babies
- Kitchen
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Shoes
- Smart Home Living Guides
- Sport & Outdoors
- Stress Relief & Relaxation
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Travel & Adventure
- Wealth
- Wellness
Paycheck Plan Checklist: Budget, Save & Spend Confidently
The Calm & Confident Paycheck Plan: Salary Mastery in 20 Easy Steps
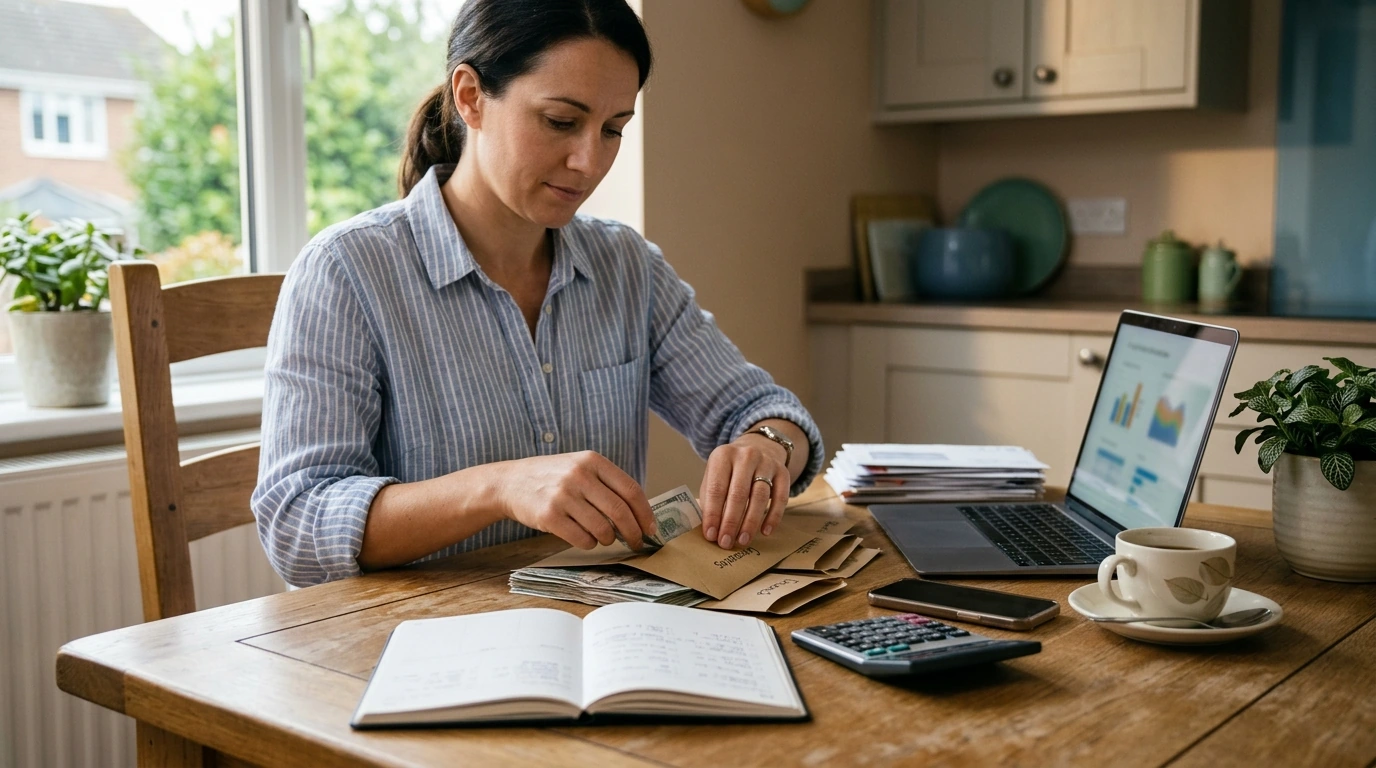
A clear paycheck routine makes money decisions feel simpler: bills get paid on time, savings happens automatically, and spending stays guilt-free because it’s planned. This step-by-step checklist turns each payday into a repeatable system that reduces surprises and builds steady progress.
What this paycheck plan helps solve
- Paychecks disappearing without a clear reason
- Bills landing at different times and causing cash-flow stress
- Saving only “if there’s anything left” at the end of the month
- Overspending because categories aren’t defined ahead of time
- Feeling uncertain about how much is safe to spend between paydays
If any of these sound familiar, the fix usually isn’t “more willpower.” It’s a simpler system: decide where your money goes before it starts leaking into unplanned purchases and last-minute bill scrambling.
Start with the essentials: pay schedule, bills, and true income
- Write down payday dates for the next 2–3 months (include bonuses/irregular pay if relevant)
- List all bills with due dates, minimum payments, and which are fixed vs. variable
- Calculate take-home pay per paycheck (after taxes, benefits, and deductions)
- Identify “annual” or “sometimes” expenses (car registration, holidays, back-to-school) and convert them to a per-paycheck amount
- Choose a home base for the system: a budgeting app, spreadsheet, or paper tracker that will be updated every payday
Paycheck planning snapshot
| Item | What to record | Why it matters |
|---|---|---|
| Pay schedule | Payday dates and frequency | Prevents gaps and late payments |
| Fixed bills | Rent/mortgage, utilities base, subscriptions | Sets the minimum you must cover |
| Variable bills | Groceries, fuel, utilities swings | Creates realistic spending targets |
| Sinking funds | Irregular expenses divided per paycheck | Avoids “surprise” costs |
| True take-home | Net income per paycheck | Keeps the plan grounded in reality |
For practical budgeting guidance and worksheets, the Consumer Financial Protection Bureau (CFPB) has free resources that pair well with a payday routine.
The 20-step paycheck routine (a repeatable checklist)
Use this as your “payday reset.” The goal is to make the next 2–4 weeks predictable—even if life isn’t.
- Confirm the paycheck amount received (compare to expected net pay).
- Set aside minimum bill money first (cover essentials before anything else).
- Fund priority goals next (emergency fund, debt payoff, upcoming known expenses).
- Allocate category amounts for variable spending (groceries, transport, personal).
- Create a buffer line item (even $10–$25 per paycheck builds resilience).
- Pay bills early when possible to reduce mental load and prevent late fees.
- Automate transfers on payday (savings, sinking funds, debt extra payments).
- Use separate “buckets” if helpful (second checking account or sub-accounts).
- Assign every dollar a job before spending (including fun money).
- Set a weekly spending pace based on days until next paycheck.
- Track purchases quickly (daily or every other day to avoid backlog).
- Run a mid-paycheck check-in (adjust categories before money runs out).
- Cap discretionary spending with a clear limit (cash envelope or card limit).
- Handle variable bills with a target + cushion (avoid underfunding utilities).
- Plan for meals and essentials early (reduce impulse spending).
- Put windfalls to work using a simple rule (e.g., 50% goals, 50% enjoy/needs).
- Review subscriptions quarterly (cancel anything not actively used).
- Audit bank fees and interest (avoid paying for things that add no value).
- End-of-paycheck reset (note what worked, what didn’t, and why).
- Monthly review: raise goals gradually as stability improves (small increases stick).
Tools that make the routine easier (simple, not complicated)
If you like having something you can check off quickly, a printable can keep the process consistent even when your week is busy. Consider keeping your checklist near your laptop or wherever you pay bills.
- The Calm & Confident Paycheck Plan printable checklist (a structured, repeatable payday routine)
- Universal Car Steering Wheel Phone Mount for Safe Navigation (useful if you do quick mid-paycheck check-ins while parked and need hands-free visibility)
- Triple-Sided Ultra-Fine Soft Bristle Toothbrush for Enhanced Oral Health (a small “planned purchase” example—easy to budget when categories are clear)
Budgeting and saving targets that stay realistic
- Use a simple priority order: essentials → minimum debt → savings goals → lifestyle spending.
- Start savings small and consistent (a fixed amount per paycheck beats an occasional large transfer).
- If income is tight, focus first on a starter emergency fund, then high-interest debt.
- Adjust targets based on actual spending data after 2–4 pay cycles.
- Treat sinking funds as “mini-bills” to prevent seasonal financial strain.
For straightforward money basics and goal-setting, MyMoney.gov is a helpful reference point. For debt and avoiding common consumer fees, the Federal Trade Commission (FTC) offers practical guidance.
How to manage your salary between paydays without guessing
Common sticking points and quick fixes
Printable checklist: set-up and weekly use
A simple next step to make it feel calm and consistent
FAQ
How much should be saved from each paycheck?
A practical starting range is 1–5% (or a small fixed amount like $10–$50) per paycheck, then increase after 2–4 pay cycles once your bill timing and spending targets are stable. Prioritize a starter emergency fund first, then focus extra money on high-interest debt.
What if bills are due before payday?
Start building a small buffer (even half a paycheck over time), and use a bill calendar so you can earmark money before it’s spent. If possible, ask providers to adjust due dates; otherwise, temporarily split payments and use sinking funds plus a one-paycheck cushion to smooth the timing.
Is a printable checklist better than a budgeting app?
Consistency matters more than the tool: a printable checklist is great for a repeatable routine and quick visibility, while an app can help automate transfers and categorize spending. Many people do best using both—paper for the plan, app for tracking.
Recommended for you
Was this article helpful?
Yes
No

Leave a comment