-
Shop
- Advanced Technologies
- AI Skills for Creators & Freelancers
- AI Client Management
- AI Ethics
- AI Mindset
- AI Tools & Prompts
- AI Writing & Content Creation
- Audio, Voice & Music
- Design & Visual Creation
- Email, Messaging & Communication
- Freelancing & Business
- Marketing, Ads & Conversion
- Productivity, Workflow & Automation
- SEO & Search Optimization
- Social Media Content & Growth
- Strategy, Planning & Analytics
- Video Creation & Editing
- AI Skills Mastery 2026 Collection
- Bathroom
- Best-Sellers
- Car Accessories
- Confidence
- Dating & Social Skills
- Digital Resources
- Easter Products
- Education & Learning
- Family & Parenting
- Fashion
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Electronics
- Home Supplies
- Jewelry
- Kids & Babies
- Kitchen
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Shoes
- Smart Home Living Guides
- Sport & Outdoors
- Stress Relief & Relaxation
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Travel & Adventure
- Wealth
- Wellness
Car Worth It? Find Your Break-Even Miles per Month
Start With the Real Costs: Fixed vs. Variable
A car is only “worth it” when the value you get (mobility, time saved, flexibility) is greater than the all-in cost you pay. The tricky part is that many of the biggest expenses don’t care whether you drive one mile or one thousand—so a car that mostly sits can quietly become a high-cost subscription.
Start by splitting costs into two buckets:
- Fixed costs (you pay these even if the car never moves): loan/lease, insurance, registration/taxes, parking, and baseline depreciation.
- Variable costs (these rise with mileage): fuel or charging, routine maintenance, tires, tolls, and mileage-based wear.
For newer vehicles, depreciation is often the single biggest line item. For older paid-off cars, depreciation may shrink, but reliability and repair risk become the deciding factor—especially if breakdowns could cause missed shifts, childcare complications, or last-minute expensive rentals.
| Cost type | Examples | How to estimate quickly |
|---|---|---|
| Fixed | Payment or lease | Monthly statement or quoted lease |
| Fixed | Insurance | Annual premium ÷ 12 |
| Fixed | Registration/taxes | Annual total ÷ 12 |
| Fixed | Parking (home/work) | Monthly garage/street permit costs |
| Fixed | Depreciation | Expected yearly value drop ÷ 12 |
| Variable | Fuel/charging | Miles ÷ MPG × price per gallon (or kWh/mi × electricity rate) |
| Variable | Maintenance/tires | Set aside a per-mile amount or use prior receipts |
| Variable | Tolls/fees | Average monthly total based on routine trips |
The Break-Even Rule: When Ownership Beats Alternatives
The cleanest way to decide is to compare:
- Monthly cost of ownership = Fixed monthly costs + (variable cost per mile × miles driven per month)
- Monthly cost of not owning = transit passes + rideshare/taxi + rentals + delivery fees attributable to not driving
Then calculate a break-even mileage point:
Break-even miles per month = (Alternative monthly cost − Fixed ownership cost) ÷ Variable cost per mile.
- If the break-even number is negative, fixed costs are already too high: owning costs more than alternatives even at zero miles.
- If alternatives swing month to month (weather, travel, surge pricing), run a low/medium/high range to see where the decision flips.
To sanity-check your assumptions, compare your per-mile costs with benchmarks like AAA’s “Your Driving Costs” and (for a broad reference point) the IRS standard mileage rates. They’re not personalized to your car, but they help catch underestimates.
Simple break-even example (fill with personal numbers)
| Input | Example value | Notes |
|---|---|---|
| Fixed ownership costs (monthly) | $650 | Payment + insurance + parking + registration + depreciation |
| Variable cost per mile | $0.25 | Fuel/charging + maintenance allocation |
| Alternative costs (monthly) | $450 | Transit + occasional rideshare/rentals |
| Break-even miles/month | Not reachable | Alternative < fixed, so owning costs more even at 0 miles |
| Alternative costs (higher-use month) | $900 | More rideshare + weekend rental |
| Break-even miles/month | 1,000 miles | (900 − 650) ÷ 0.25 = 1,000 |
Practical Driving Thresholds by Lifestyle (Quick Reality Check)
Location can shift the break-even dramatically. In dense urban cores, parking and insurance can push fixed costs so high that you need a lot of miles to justify ownership. In suburbs or rural areas, alternatives may be so limited that even moderate use makes a car the most workable option. For broader context on how Americans travel, the Bureau of Transportation Statistics (BTS) is a helpful reference point.
| Scenario | Typical pattern | Decision lever |
|---|---|---|
| Remote worker in a city | Few trips, lots of delivery | Parking + insurance vs. rideshare/rental days |
| Commuter 3–5 days/week | Regular miles and time pressure | Time value + reliability + monthly cost certainty |
| Family logistics | Short trips + weekend errands | Car-seat hassle + schedule flexibility |
| Occasional road trips | Low monthly miles but bursty travel | Rental cost for peak weekends vs. owning year-round |
Hidden Deal-Breakers That Change the Math
Checklist for a fair comparison
| Factor | Add to ownership cost? | Add to alternatives cost? |
|---|---|---|
| Work parking | Yes (monthly) | No |
| Street tickets/permits | Yes | No |
| Rideshare surge pricing | No | Yes |
| Rental insurance/fees | No | Yes |
| Lost time on transit | Optional (time value) | Optional (time value) |
| Repair risk buffer | Yes (monthly reserve) | No |
Decision Framework: Keep, Buy, or Go Car-Free
| If this is true… | Then consider… | Why |
|---|---|---|
| Car sits most weeks and parking/insurance are high | Selling and using rentals/rideshare | Fixed costs dominate |
| Car is paid off and reliable, with low insurance | Keeping it even with lower mileage | Low fixed costs improve break-even |
| Frequent rentals or rideshares exceed a monthly car budget | Buying/keeping a car | Alternatives already act like a car payment |
| Unreliable car causes missed obligations | Replacing with a more reliable option | Downtime is a hidden cost |
Small Upgrades That Increase Practical Value When Driving Less
- How Much Driving Makes a Car Worth It – Practical Guide to Decide How Often Do I Need to Drive to Justify a Car
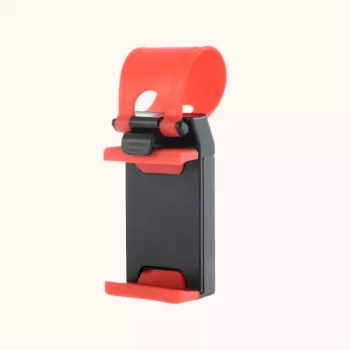
- Universal Car Steering Wheel Phone Mount for Safe Navigation
FAQ
Is it worth owning a car if it’s only driven on weekends?
It’s often borderline: compare your fixed monthly costs (insurance, parking, depreciation) against weekend rentals and occasional rideshare. Weekend-only ownership tends to work best when parking is free/cheap, the car is paid off, and rentals nearby are pricey or inconvenient.
How many miles per month justify a car payment?
There’s no universal number because fixed costs vary so much by location and vehicle. Use break-even miles = (alternative costs − fixed ownership costs) ÷ variable cost per mile, and run a range for low/medium/high months to see where ownership starts to win.
Should a rarely driven car be sold or kept for emergencies?
Compare the annual fixed cost of keeping it (insurance, registration, parking, depreciation) to the realistic cost of emergency alternatives (rental availability, taxi/ride access, delivery). If it’s mainly peace of mind, lowering insurance coverage where appropriate, reducing parking costs, or keeping a cheaper vehicle can improve the math.
Recommended for you
Was this article helpful?
Yes
No

Leave a comment